Share this article


Topics on this page
On August 29, 2026, The Wall Street Journal referred to PPLI as “A Roth-IRA on Steroids.” Why? What is PPLI? And should I have one? Let’s start from the beginning.
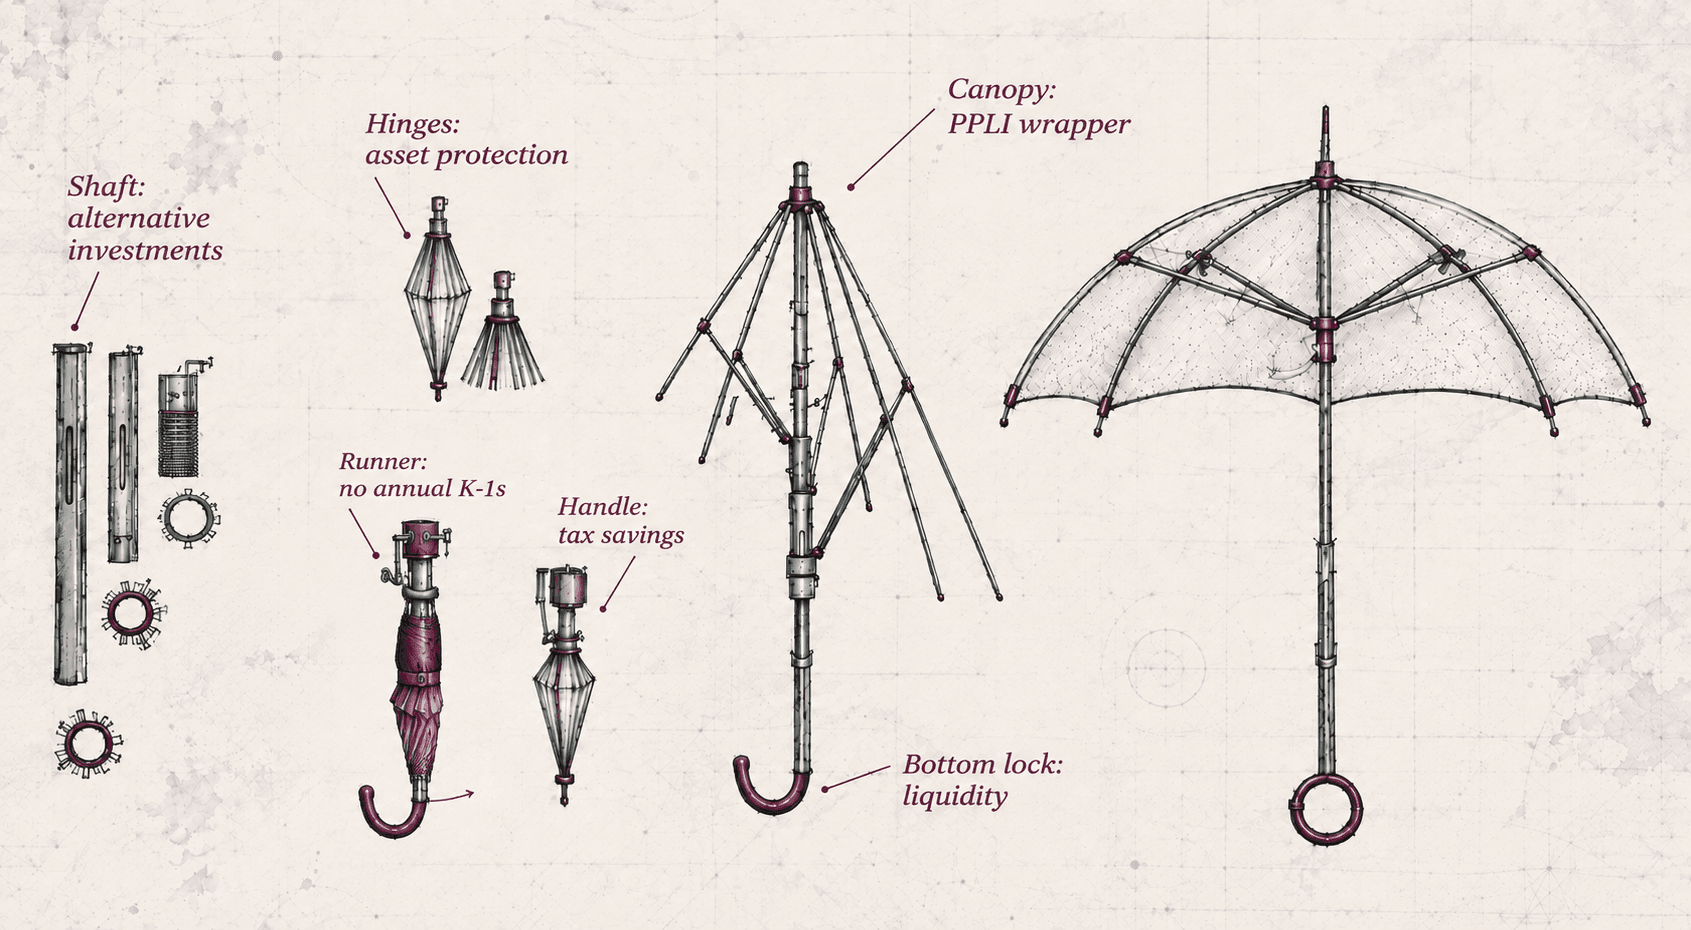
Private Placement Life Insurance (PPLI), also referred to as PPVUL, is specialized life insurance designed for high-net-worth individuals seeking tax-efficient ways to grow and preserve their assets. Unlike traditional life insurance, PPLI offers policyholders the ability to invest in a broad range of investment options, including alternative assets like hedge funds, private equity, and real estate. These investments grow tax-deferred, allowing for potential tax savings and increased wealth accumulation over time.
What is PPLI?
At its core, PPLI is a form of variable life insurance, which is a type of permanent life insurance. There is a lot of confusion, both online and offline, about what constitutes permanent life insurance, so it's important to first understand this fundamental classification. The defining feature of permanent life insurance, beyond the promise of a death benefit payout regardless of timing of death, is the presence of a cash value account within the policy. Some of the premium paid goes towards the death benefit and some in the cash value account. Exactly how much goes where, and who takes the risk of the underlying performance of the cash value, are what differentiates one type of permanent life insurance over another. PPLI, along with Whole Life, Guaranteed Universal Life (GUL), Index Universal Life (IUL) and Variable Universal Life (VUL), are forms of permanent life insurance.
In a PPLI, the policy's cash value is invested through Insurance Dedicated Funds (IDFs), selected and approved by the insurance company, which can provide access to strategies such as hedge funds, private credit, private equity, and other institutional investments, depending on the carrier and policy structure. Through the use of Separate Managed Accounts (SMAs), which are not a focus of this article, the policy’s cash value can be invested in a wider set of investment options other than insurance funds. For a wealthy investor, the insurance wrapper can be valuable because investment income and gains generally are not subject to current federal income and capital gains taxation while they remain inside a qualifying policy.
How does PPLI Work?
A typical PPLI strategy involves several components:
You contribute premiums to a life insurance policy.
The policy's cash value is allocated among eligible investment strategies.
Investment returns accumulate inside the policy.
Principal and investment proceeds can be utilized via a properly structured loan.
The policy provides a death benefit to designated beneficiaries.
If properly structured and maintained, the policy receives favorable tax treatment under the Internal Revenue Code.
PPLI is not simply an investment account with a different name. It is a legal insurance contract, and maintaining its tax treatment requires compliance with specific rules governing life insurance, investment diversification, and policy design. IRC §7702 establishes the requirements for a contract to qualify as life insurance for federal tax purposes.
What are the Tax Advantages of PPLI?
1. Tax-free investment growth (tax-alpha)
Investment income and capital gains, inside a qualifying life insurance policy, are not taxed annually as they would be in a conventional investment account. That means interest, dividends, and realized investment gains can remain invested rather than being reduced each year by income taxes. Over a long investment horizon, avoiding annual tax drag can have a meaningful effect on compound growth.
2. Tax-efficient access to policy value
A properly structured life insurance policy can provide access to cash through withdrawals and policy loans without creating income tax, subject to the policy's basis, loan terms, and applicable tax rules. This feature can provide wealthy investors with a source of liquidity while allowing the remaining assets to continue growing inside the policy. Policy design is critical, as rules such as Modified Endowment Contract (MEC) can change the tax treatment of policy distributions.
3. Income-tax-free death benefit
One of the most important benefits of life insurance is the generally income-tax-free treatment of death proceeds. IRC §101(a), subject to a few specific exceptions, excludes from ordinary income - the life insurance proceeds paid out in the event of death. For a wealthy family, this can make PPLI particularly interesting as part of a multigenerational wealth strategy.
4. Estate-planning benefits
Ownership structure matters. When life insurance is appropriately owned through an irrevocable trust or another suitable structure, the death benefit may be excluded from the insured's taxable estate. This can create an additional layer of estate-planning efficiency, and immediate liquidity. That is why PPLI should generally be evaluated as part of a broader wealth and estate plan rather than as an isolated insurance purchase.
Why Might an Investor Consider PPLI?
PPLI isn't appropriate solely because someone has a high net worth. It's also not just for billionaires or centi-millionaires, as was the case prior to 2021.
PPLI insurance tends to appeal to high-net-worth individuals and families who are insurable, desire exposure to alternative investments and significant death benefit coverage, and want flexibility of investment options within their policy.
PPLI is generally available to those who meet certain criteria, including:
- Investible assets of $7-10 million and up
- Meaningful, taxable investment income or capital gains
- A legitimate life insurance need or estate-planning objective, and comfort with a certain level of insurance complexity
- A desire to meaningfully invest in alternative assets with an investment horizon of at least 10 years
- The ability to fund at least $250,000 in annual premiums for the first several years of a new policy
The question isn't simply: “Do I qualify for PPLI?”
A better question is: “Would placing a portion of my long-term investment strategy inside a PPLI policy create enough value to justify the costs and complexity?”
For many wealthy investors in high tax jurisdictions, the answer is often yes.
Is PPLI an Insurance Product?
The U.S. Treasury has described PPLI as an investment-oriented form of life insurance generally used by very high-net-worth individuals, particularly where income-tax and estate-planning considerations are important. For individuals or families, PPLI is best evaluated within the context of the entire financial ecosystem.
That means looking at:
Taxable investments
Investment strategy
Private investments
Liquidity needs
Existing life insurance
Business interests
Estate-planning structures
Family objectives
Trusts
Legacy goals
This planning-first approach is why GenNXT works hand-in-glove with your investment advisor, estate planning attorney, CPA and family office to properly assess and structure a PPLI solution. We have built the tools that make it possible for investment professionals to include PPLI in their planning, instead of handing you off to a traditional insurance brokerage who lacks visibility across your financial estate. GenNXT provides unbiased solutions and excels at integrated coordination.
What are the Downsides of PPLI?
Without a nuanced understanding of pros and cons, PPLI can sound too good to be true. This skepticism and lack of understanding has inhibited adoption of PPLI among wealthy investors. To be clear, PPLI is not a tax-free investment account with no strings attached.
It involves:
- Insurance costs and investment-management expenses
- Policy-design considerations and important decisions
- Time and effort to secure underwriting approval
- Liquidity considerations for funding the policy
The economics therefore need to be modeled carefully. PPLI also requires ongoing compliance: meeting investment diversification requirements under IRC §817(h), life insurance qualification under §7702, and following other rules to preserve the intended tax treatment. Working with a PPLI expert like GenNXT is the difference between creating a financial headache or the peace of mind of lasting legacy.
Is PPLI Right for You?
With expert counsel, PPLI can be a powerful planning tool in one's overall estate plan, but it isn't universally appropriate. A thoughtful evaluation should begin with key considerations:
- What is the money to be used for?
- How long is it expected to remain invested?
- How much tax drag is currently affecting your portfolio?
- What assets are intended for heirs?
- What role does life insurance play in the overall estate plan?
From there, advisors can model whether PPLI offers a meaningful advantage compared with maintaining the assets in a traditional taxable investment account or using other planning strategies such as GRATs, or CRTs or other options.
The Bottom Line
Private Placement Life Insurance can combine life insurance protection, tax-efficient investment growth, and wealth-transfer planning in a single structure. For wealthy investors with substantial long-term assets, the potential to compound investment returns without annual income taxation makes PPLI worth investigating.
However, PPLI is a sophisticated strategy. Its benefits depend on proper policy design, investment allocation, compliance adherence, ownership structure, and long-term planning. The best starting point isn't a policy illustration. It's a conversation about what your wealth is intended to accomplish—and how efficiently your current strategy is accomplishing it. Reach out to GenNXT to start that conversation.